Are you or a loved one searching for a trusted sober living program? Give us a call!  310-953-4075
 310-953-4075 Paying for sober living often becomes a shared responsibility, especially when a resident is still working toward steady employment and reliable income. A family may cover the cost at first, the resident may contribute what they can, or the payment arrangement may change as their financial situation improves.
The important part is understanding what each source of support can realistically provide. Family assistance, resident income, insurance, and certain public funding options work differently, and some may not apply to a particular situation.
For families considering paying for sober living for a family member, having a clear plan can make the financial side easier to manage. Knowing the monthly cost, how long you can contribute, what the resident will eventually take on, and how other expenses will be handled can prevent the arrangement from becoming unclear or open-ended.
The first step is understanding the different ways sober living can be paid for and which ones may apply to your family.
There is no single payment arrangement used by every sober living home. Before making plans, ask the residence about its current cost, payment policies, and any financial options that may apply.
Research on California sober living houses also shows that residents may rely on different financial resources to cover housing costs. In one study, about 90% of residents used personal resources, including employment earnings, savings, family resources, or Social Security Income, to pay for housing.
About 10% received support through a specific California corrections-related program. Because the study examined a particular group of sober living houses, these percentages should not be treated as a standard breakdown for every sober living home.
The four main sources families are likely to consider are the resident, family members, insurance, and eligible public funding.
Some residents pay for sober living using employment income, savings, or a combination of the two. Others may need time to establish reliable income before they can cover more of their housing expenses.
There is no specific income level that automatically makes sober living affordable. The resident needs to consider the monthly housing cost alongside transportation, food, phone bills, debt payments, and other regular expenses.
If employment is part of the plan, it can help to look at:
As income becomes more consistent, the resident may be able to take responsibility for a larger portion of the cost. Money management can help residents work on budgeting and financial responsibilities while preparing for greater independence.
Parents, spouses, or other relatives may decide to pay some or all of the sober living cost, particularly while the resident is getting established. Understanding the cost of sober living in Los Angeles can help families estimate what they may need to contribute.
Family assistance does not have to mean agreeing to cover every expense indefinitely. You can decide on a specific contribution, identify what it covers, and establish when the arrangement will be reviewed.
Where the residence permits it, families may also prefer to pay housing costs directly to the sober living home rather than transferring the housing money to the resident. Before doing so, confirm the home's payment procedures and what documentation you will receive.
If you are considering Bridges, ask the team directly about its current payment process rather than assuming a particular direct-pay arrangement is available.
Health insurance and the cost of living in a sober living home are not necessarily the same thing.
Sober living primarily provides a recovery-focused living environment rather than the clinical services typically covered by health insurance. A person may have insurance coverage for eligible healthcare services they receive separately, but that does not automatically mean the cost of living in a sober living home is covered.
Because plans and benefits differ, families should check the person's insurance benefits and ask the sober living home what costs residents are responsible for before making financial plans.
Some people may qualify for housing or other financial assistance through local public programs. However, the programs available, eligibility requirements, and types of housing they can support differ by location and individual circumstances.
If paying privately is not realistic, a useful starting point is to contact local housing or behavioral health resources and ask specifically whether there are programs that can help with recovery housing or sober living costs. Before relying on any program, confirm:
This keeps the section useful without suggesting that county funding is automatically available to someone simply because they need help paying for sober living.
Once a family decides to contribute, agreeing on the details early can prevent uncertainty later. A parent may be comfortable covering several months of housing, for example, without being able to make an open-ended financial commitment.
The arrangement does not need to be complicated. It should simply make clear who is paying for what and when the plan will be reviewed.
Start with what your family can realistically afford rather than deciding solely from the amount being requested.
Clarify:
A review date can be especially useful. Instead of promising to pay “until you're ready,” you might agree to review the situation after a defined period based on employment, income, housing plans, and current circumstances.
This gives everyone a point at which to discuss what comes next without assuming the original arrangement must continue unchanged.
Next, decide how the money will actually move.
If the sober living home accepts direct family payments, you may choose to pay the residence rather than transferring housing money to the resident. Ask how payments are processed, what they cover, and whether receipts or other payment records are provided.
Keep housing payments separate from other financial support where possible. This makes it easier to understand how much your family is contributing toward the residence versus transportation, groceries, phone bills, or other needs.
For Bridges specifically, confirm the current family-payment process directly with the admissions team before setting up an arrangement.
A financial plan should also account for the possibility that circumstances change.
Discuss in advance:
The purpose is not to predict every possible situation. It is to avoid having to make every financial decision for the first time during a difficult moment.
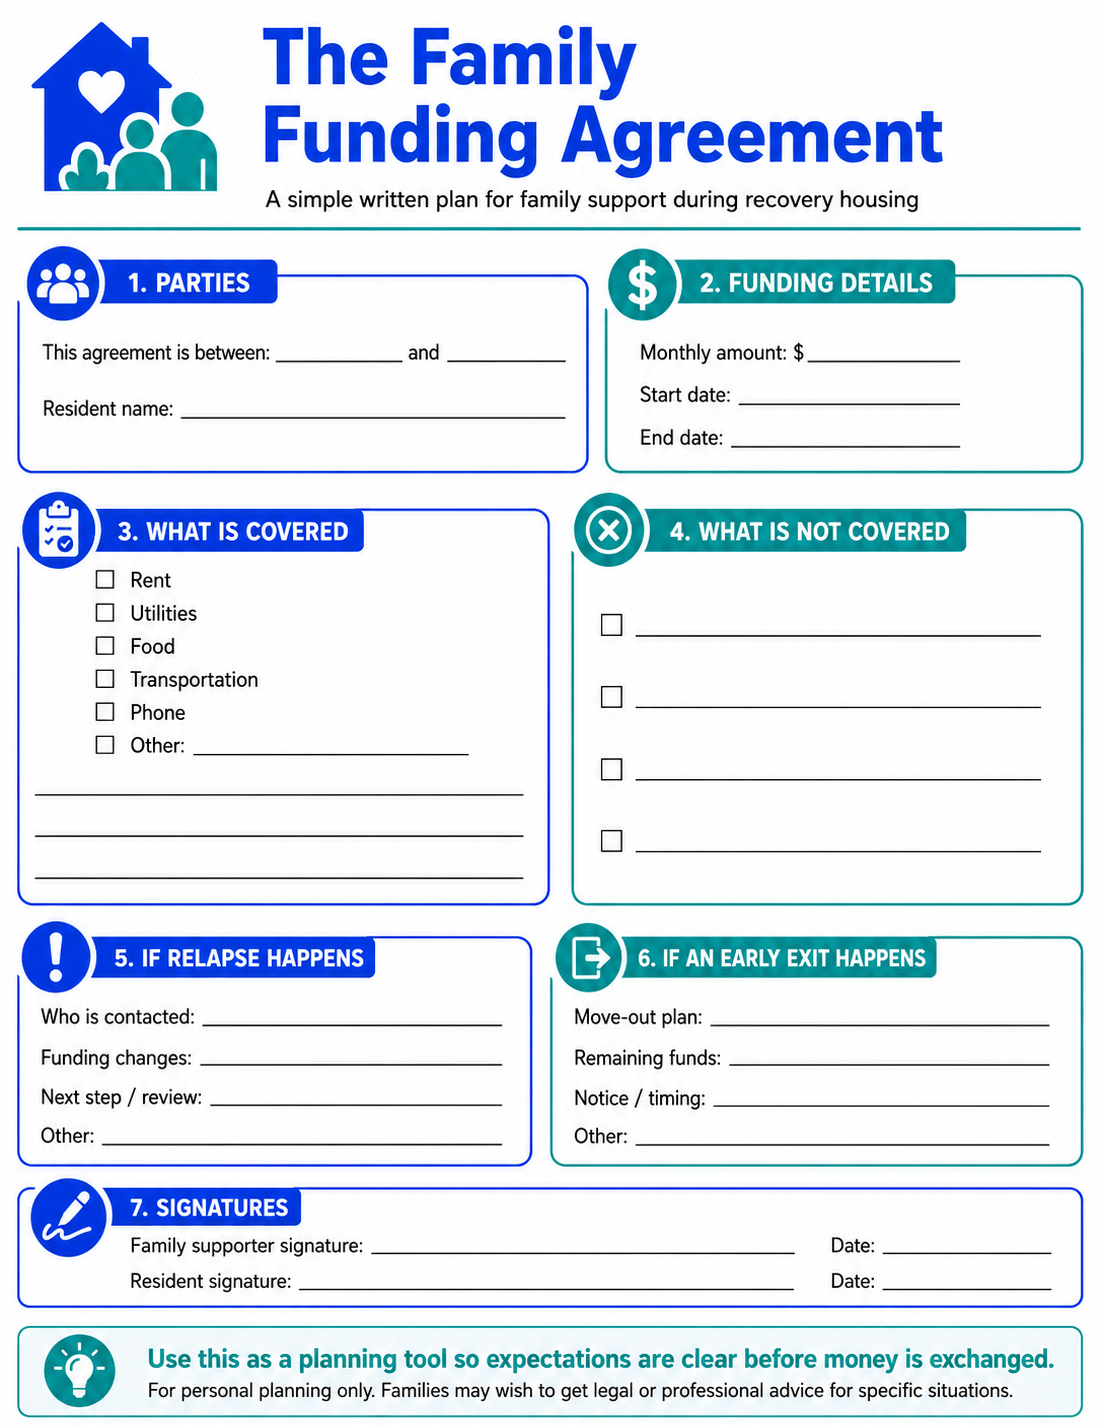
Housing is only one expense. Residents may also need money for transportation, groceries, phone service, work-related expenses, and personal necessities.
Some families are comfortable providing a set amount of spending money. Others prefer to pay for particular needs without providing unrestricted cash. Either approach can be discussed openly with the resident.
Depending on what works for your family, options can include:
For example, if transportation is the primary concern, paying for a transit pass may address that expense directly. If groceries are the concern, a grocery card can provide a defined amount for food.
The goal is not to monitor every purchase. It is to decide together what the family has agreed to cover and how that support will be provided.
Some families reach this decision after they have already spent a significant amount trying to help someone they care about. At that point, another request for financial support can bring up frustration, worry, exhaustion, or uncertainty about whether paying again is the right decision.
Money already spent is important to acknowledge, but it should not be the only reason to continue or stop financial support.
Instead, evaluate the current request on its own:
It is reasonable for a family to have financial limits. Supporting someone does not require committing to an amount or timeframe that the family cannot sustain.
It can also help to separate the decision about money from the broader relationship. A family can remain supportive while still being clear about what it can and cannot financially provide.
Family support services can also help families think about communication, boundaries, and their role during recovery.
There is no single answer to who pays for sober living homes. The resident may cover the cost, family may contribute, and certain eligible individuals may have access to public assistance. Insurance coverage requires careful distinction between housing costs and separately covered healthcare services.
For families who decide to help, clarity can make the arrangement easier to manage. Agree on the amount, duration, expenses covered, resident contribution, and what will happen if circumstances change.
If your family is considering Bridges, ask about current costs and payment procedures before deciding what you can contribute. Having the details in front of you can help you make a financial decision that is realistic for both the resident and the family.
Sober living may be paid for by the resident, family members, or a combination of sources. Certain eligible individuals may also have access to public or community housing assistance.
Yes, families may choose to contribute toward sober living costs. Before doing so, clarify how much you will pay, what the contribution covers, how long it will continue, and how payments will be handled.
Yes. Residents who are working may use their income to cover some or all of their sober living expenses. Whether full self-pay is realistic depends on income, housing costs, and other regular expenses.
Insurance may cover eligible healthcare services, but that does not necessarily mean it covers the room-and-board cost of sober living. Check the person's specific benefits and the residence's payment requirements.
Some local programs may provide housing assistance to people who meet their eligibility requirements. Whether that assistance can be used for sober living depends on the specific program, location, residence, and available funding. Contact the relevant local program directly before including public assistance in your payment plan.
Depending on what you and the resident agree on, you might use transit passes, grocery cards, prepaid cards with a set balance, direct bill payments, or purchase specific necessities. The best arrangement is one that is clear to everyone involved.